INTERIM HOME CARE UTAH
Aid and Attendance Rates: What Helps and What to Avoid
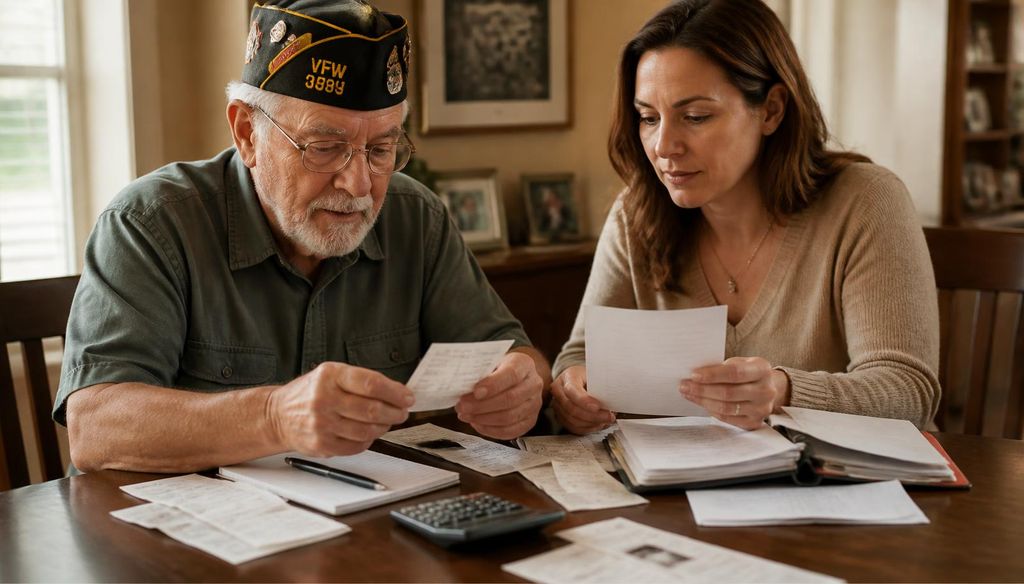
We've covered the base Aid & Attendance rates elsewhere. This is about the part that actually determines what a specific family receives: unreimbursed medical expenses, and the documentation choices that increase or reduce your effective rate.
The Rate Isn't Automatic — Income Matters
Aid & Attendance's maximum rate isn't paid to everyone who qualifies for the benefit category — your actual payment is reduced based on your countable income. The good news: unreimbursed medical expenses, including the cost of home care itself, can be deducted from that countable income, which often brings a family much closer to the maximum rate than their raw income alone would suggest.
What Helps: Documenting Medical Expenses Thoroughly
Keep records of home care costs, medical insurance premiums, prescription costs, and other out-of-pocket medical expenses. These directly reduce countable income in VA's calculation — the more thoroughly documented, the more accurately your rate reflects your real financial picture, rather than a income figure that doesn't account for what you're actually spending on care.
What Helps: Filing With Complete Financial Documentation From the Start
Submitting complete income and expense documentation with the initial application, rather than a partial picture that VA has to request more information about, both speeds up the claim and reduces the chance of an inaccurate initial rate determination that later needs correcting.
What to Avoid: Asset Transfers Right Before Applying
VA applies a look-back period on assets transferred for less than fair value specifically to qualify for benefits. Giving away money or property shortly before applying can trigger a penalty period that delays your actual rate, even if you'd otherwise qualify. This kind of planning needs to happen well in advance, not as a last-minute move.
What to Avoid: Incomplete or Vague Documentation
A claim with vague or incomplete financial documentation often gets sent back for more information, which delays when you start actually receiving the rate you're entitled to. This is one of the most common, most avoidable sources of delay.
Get Help Getting This Right
An accredited Veterans Service Officer or VA-accredited claims agent can review your specific financial documentation before you file, and help make sure your claim reflects the actual rate you're entitled to — often at no cost.
How This Connects to Home Care
Since home care costs themselves count as a deductible medical expense, keeping clear records of what you're paying us — or any care provider — is directly relevant to your Aid & Attendance rate, not just a bookkeeping detail.
Our 7th Week Guarantee
No long contracts. If you don't feel the difference after six weeks of care at 20 or more hours a week, your seventh week is free.
Get Started
Call us at (801) 401-3515 to talk through your situation.
Learn more about VA Aid & Attendance eligibility and rates, how to apply, and the net worth limit.
Veterans & VA Home Care Benefits
More from this series
Understanding the VACP TREAS 310 Deposit | Interim
A deposit labeled VACP TREAS 310 in your bank account is a legitimate VA benefit payment. Here's exactly what it means and why it appeared.
What Does VACP TREAS Mean on Your Bank Statement? | Interim
VACP TREAS deposits come in a few variants beyond the common 310 code. Here's how to read any version of this transaction on your bank statement.
Home Care Benefits at 40 Percent Service Connected | Interim
A 40% disability rating doesn't qualify for PCAFC's caregiver stipend, but several other real home care benefits don't require any specific rating at all.
How Much Does the VA Pay for in Home Care? | Interim
A quick, consolidated answer — every VA program's approximate dollar figure for home care, in one place, with links to the full detail on each.